
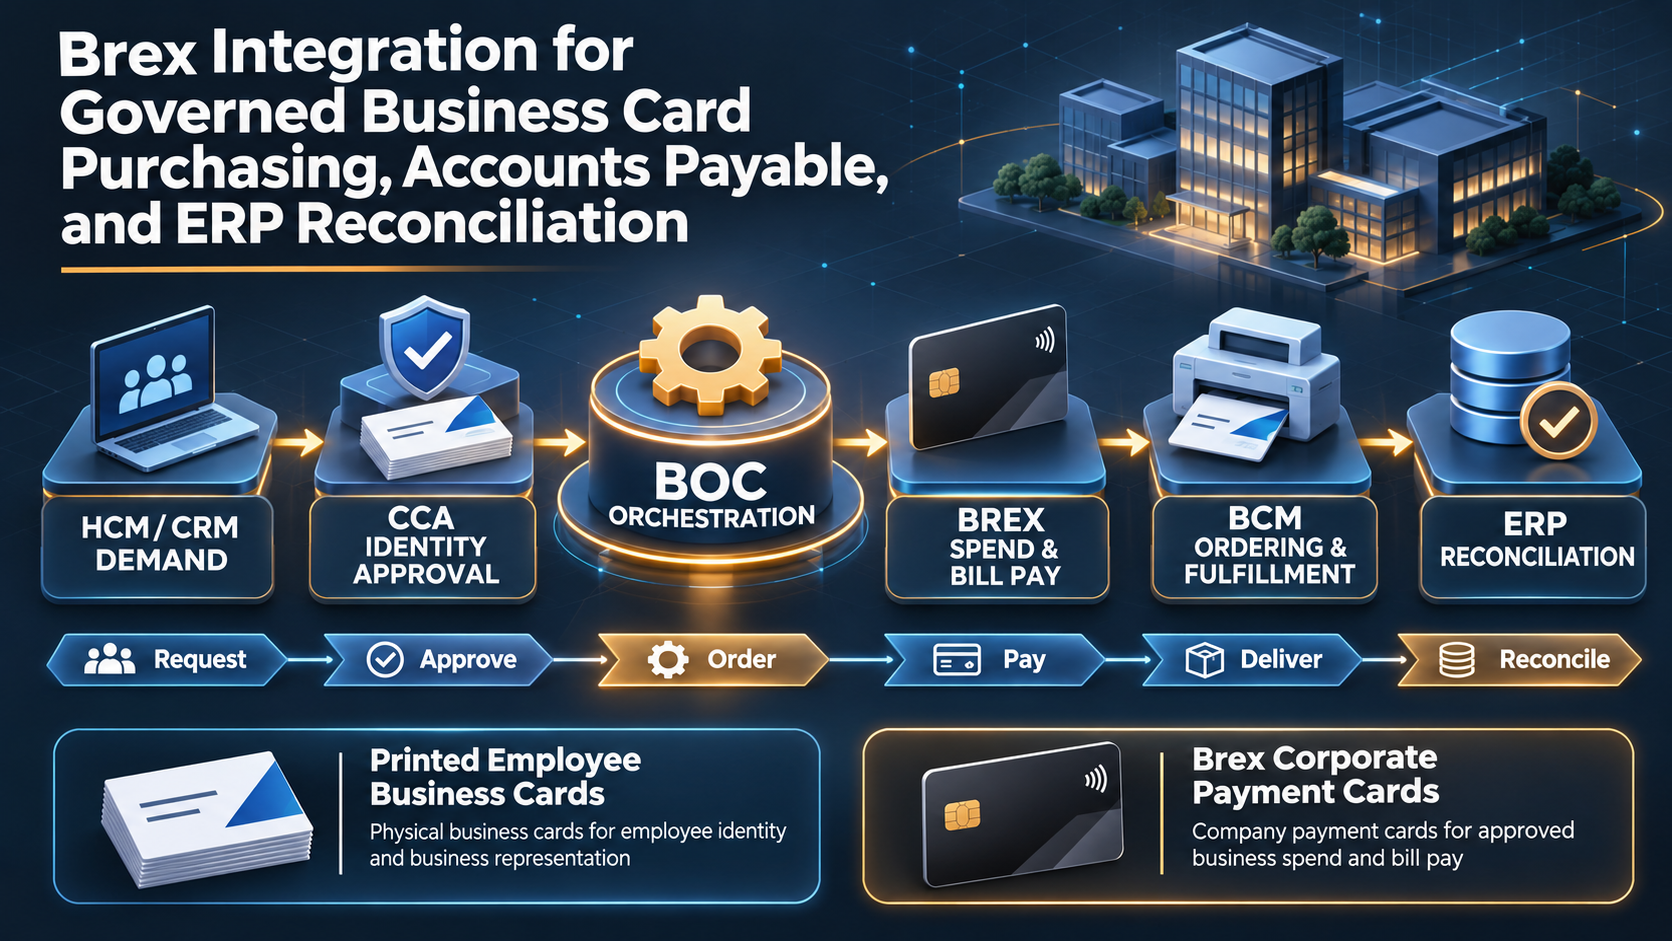
Connecting HCM and CRM demand, CCA identity governance, BCM fulfillment, Brex spend controls, Bill Pay, and accounting evidence through BOC.
In a Brex business card procurement integration, Brex can support configured spend requests, approval chains, budgets, spend limits, purchase orders, corporate cards, Bill Pay, and ERP-connected accounting. Those capabilities control money and financial evidence; they do not approve the public identity printed on an employee business card or prove that the correct cards were produced and delivered. BOC governs the cross-system outcome, CCA governs printable identity, and Business Card Manager governs ordering and fulfillment.
Printed Business Cards and Brex Corporate Cards Require Different Governance
A printed business card and a Brex corporate card may both be called cards, but they carry different risks and authorities. The printed artifact publishes an employee name, role, contact data and brand identity. The corporate payment card provides controlled access to company funds. Treating one approval as authority for the other creates a gap between identity governance and financial governance.
CCA approves the printable identity version. Business Card Manager, or BCM, converts that approved specification into an order and manages proof, production, shipment, delivery, correction and reprint. Brex may control a spend request, budget, limit, purchase order, payment card, bill and accounting export according to the customer configuration.
BOC connects the domains while preserving their boundaries. A Brex approval can authorize spend but cannot approve a title for publication. A BCM shipment can demonstrate physical delivery but cannot prove correct coding, payment or ERP acceptance. The case closes only when supported identity, commercial, fulfillment and financial evidence agree.
Why Business Card Purchasing Needs More Than a Finance Workflow
Business-card demand may begin with a new hire, transfer, promotion, office move, territory assignment, event or partner campaign. The requirement crosses workforce or customer data, identity rules, brand policy, commercial approval, supplier production, logistics, accounts payable and accounting. A completed task inside one system is therefore not the same as a completed business outcome.
An approved spend limit may exist before CCA approves the identity. A correctly coded bill may refer to cards printed with an obsolete title. A BCM delivery may be accepted while the bill is duplicated or rejected by the ERP. BOC prevents these partial successes from being mistaken for end-to-end closure.
The governed case retains the source event, CCA version, Brex request and approval, budget or spend limit, PO or payment path, BCM order and fulfillment history, bill and payment evidence, ERP response, exceptions and closure authority. Teams can investigate one trace without assigning universal ownership to any single application.
Keep Authority Clear Across HCM, CRM, CCA, BCM, Brex, and the ERP
HCM remains authoritative for worker status, manager, organization, cost center, location and effective dates. CRM may be authoritative for event, campaign, partner or territory demand. These sources establish why cards are required and when the requirement is eligible; they do not approve printable identity or vendor payment.
CCA governs the public-facing name, title, contact details, location, template and approved identity version. BCM is the business-card ordering system and contracted vendor, responsible for proof, production, shipment, delivery and corrections. Brex governs configured spend-management and Bill Pay activity. The ERP or accounting system retains the authoritative financial master and posting records defined by the customer.
BOC governs transitions, prerequisites, correlation, duplicate prevention, exception ownership, reconciliation and closure. This division allows each system to do the work it is designed to do without letting procurement become an identity editor or fulfillment become an accounting substitute.
What Brex Contributes to the Connected Process
Brex documents request types for governed employee spend, including procurement use cases, with customizable policy rules and approval chains. Depending on plan and configuration, an approved request can issue a spend limit, purchasing card or purchase order. Spend limits can support card purchases, reimbursements or bill payments and can carry purpose-specific controls.
Brex Bill Pay supports invoices uploaded or forwarded for draft payment creation, policy-based approvals, scheduling, payment and ERP-related fields. Brex also documents purchase-order management and two-way matching of bills to POs. These functions can control the financial path for BCM purchases while BCM remains responsible for the physical order and outcome.
Brex lists direct-sync ERP integrations and manual import or export options. Availability varies by plan, add-on, ERP, entity, region, payment method, role and configuration. This article describes a configurable integration architecture; it does not claim a universal released native connector among Brex, BOC, CCA and BCM.
The Governed Brex Business Card Purchase to Payment Lifecycle
| Lifecycle stage | Authoritative context | BOC control | Required outcome |
|---|---|---|---|
| Demand | HCM or CRM source event | Qualify purpose, timing, owner and duplicate state | Trusted BOC case |
| Identity | CCA policy and approved version | Preserve identity authority and version | Approved card specification |
| Request | Brex request type and policy | Correlate need, entity, budget and approval | Authorized spend path |
| Order | BCM order and PO or payment reference | Prevent duplicate release and preserve lineage | Executable supplier order |
| Fulfillment | BCM proof, production, shipment and delivery | Monitor milestones and physical exceptions | Verified physical outcome |
| Bill | Brex Bill Pay and PO context | Reconcile vendor, commercial and physical evidence | Supported bill or owned exception |
| Payment | Brex payment and ERP response | Track release, return, credit and posting state | Supported financial outcome |
| Closure | Physical, financial and decision evidence | Authorize closure or assign residual work | Auditable closed case |
Qualify HCM and CRM Demand Before Spend Is Requested
BOC begins with an authenticated source event and a stable business identifier. A new hire may qualify only after the start date is confirmed. A transfer may change the title, legal entity, location, cost center, delivery address or required date. A CRM event may justify cards for a controlled participant list rather than the general employee population.
Eligibility rules should stop unsupported demand. Terminations, leave, duplicate events, incomplete profiles, expired campaigns, uncertain delivery points and missing managers create a hold or owned exception. The case records why cards are needed, who owns the request, which entity pays, what quantity is permitted and when the requirement becomes effective.
Only a qualified case proceeds to CCA and the Brex commercial path. The same BOC correlation key follows the requirement through identity approval, spend authorization, BCM ordering and delivery, Bill Pay, ERP synchronization and final closure.
Approve Printable Identity in CCA Before Commercial Release
BOC sends the minimum required identity attributes to CCA. CCA applies naming, title, contact, location, template and brand policy and returns an approved version. That controlled version is the specification BCM may use for proof and production.
A requester or finance approver must not repair identity in a free-text spend request, PO description, memo or bill line. When an authoritative field conflicts, BOC routes the issue back to the owning system. This prevents procurement convenience from creating an unauthorized public identity.
If the identity changes after commercial approval, BOC evaluates the production state. The request may be updated, the BCM order may be paused, or a cancellation, credit, replacement or named acceptance may be required. Both versions and the resulting decision remain linked to the case.
Use Brex Request Types and Approval Chains for the Buying Decision
Brex request types can provide a governed intake for procurement and other spend purposes. A business-card request can include the BOC case reference, legal entity, cost center, business reason, controlled quantity, needed date, destination, BCM supplier relationship and expected payment path. Policy rules can route the request according to amount, organization or other configured attributes.
The financial approver needs purpose, price, budget and ownership context. The approver does not need to reapprove the identity fields already governed in CCA. BOC verifies that the approved request and the CCA identity refer to the same case version before an order is released.
Approval chains should preserve segregation of duties. Automated approval may be appropriate for a supported low-risk request, but it must never silently approve printable identity, a physical variance or an unsupported vendor record. The rule, inputs, result and escalation route must remain explainable.
Choose the Brex Spend Limit, Purchase Card, or Purchase Order Path Deliberately
Brex documents several ways to issue approved spend, including spend limits, purchasing cards and purchase orders when available. The customer should choose the route that matches its procurement policy, supplier arrangement, accounting design and licensed capabilities. The word card must not obscure the difference between a Brex payment instrument and the printed cards being purchased.
A spend limit can establish a purpose, amount and policy boundary for BCM purchasing. A purchasing card can create a controlled payment method. A PO can document the commercial commitment and support later bill matching. BOC links the selected Brex object to the CCA version and BCM order without duplicating master data.
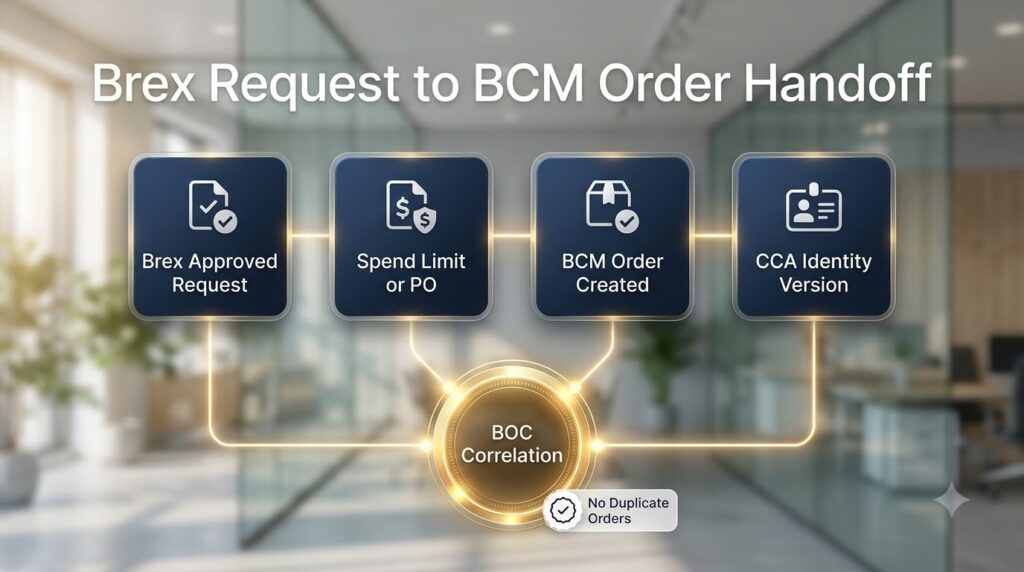
Changing routes requires control. If an approved PO path becomes a card purchase or a Bill Pay path, BOC records the reason, authority and replacement reference. Retries, manual intervention and uncertain acknowledgements use idempotency and reconciliation controls so they do not create duplicate orders or duplicate commitments.
Connect BCM Ordering and Fulfillment to the Brex Commercial Record
BCM receives the approved CCA identity version, product, quantity, destination and commercial reference. It creates the supplier order, manages the proof and production process, ships the cards and returns milestone and exception evidence. BCM remains the ordering and fulfillment authority even when Brex governs the financial path.
A successful API response, portal submission, purchasing-card authorization or PO transmission does not prove that the intended BCM order exists. BOC confirms the worker or campaign context, approved version, product, quantity, address, commercial reference and BCM order number before the transition is complete.
Shipment is not automatically acceptance. BOC records delivery, recipient or receiving confirmation, shortage, damage, incorrect identity, reprint, cancellation and credit state. Physical evidence becomes a prerequisite for the customer-defined receiving, bill approval, payment and closure decisions.
Capture, Validate, and Route the BCM Bill in Brex Bill Pay
Brex Bill Pay allows invoices to be uploaded or forwarded and translated into draft payments for review. A BCM bill should carry the approved vendor and entity, invoice number, PO or non-PO route, BCM order, line items, quantity, price, freight, tax, currency, credit reference and BOC case identifier required by the customer design.
BOC validates the bill against authoritative context. It checks vendor and entity, duplicate state, reference integrity and whether the BCM order is active, fulfilled, cancelled, disputed or under correction. Missing or conflicting evidence creates an owned exception rather than an invented default.
Approval notes can explain a variance but cannot replace a governed decision. An AP reviewer cannot change the CCA identity, accept defective cards for the operational owner, or alter supplier payment details without the proper control. BOC preserves the decision maker, evidence, timestamp and downstream effect.
Match the Bill to the Purchase Order and Physical Outcome
Brex documents purchase-order management and two-way bill matching based on vendor, amount and dates. That financial match should be supplemented with the business outcome. For printed business cards, product, quantity, approved identity version, delivery destination and accepted fulfillment state matter alongside amount and PO balance.
A financial tolerance may permit a small price or freight variance, but it must never authorize an incorrect public identity or unapproved product substitution. Partial shipments, split bills, reprints, credits and replacements retain lineage to the original case so the organization can see what the supplier delivered and what finance paid.
Receiving rules must be explicit. A carrier scan may support delivery evidence without proving recipient acceptance. The customer defines which evidence is sufficient to record receipt, approve a bill, release payment and close the operational case.
Integrate Brex with the ERP Without Competing Master Data
Brex documents direct-sync integrations for several ERP and accounting platforms, as well as custom accounting and manual import or export options. The implementation must validate the supported interface for bills, payments, card expenses, vendors, categories, GL accounts, departments, projects, entities and other required dimensions.
The ERP or accounting platform remains authoritative for the customer-designated financial masters and postings. BOC must not invent a substitute vendor, account, entity, dimension, tax treatment or payment term when the required record is missing or inactive. It retains the failed context and assigns resolution.
Every interface needs authentication, least privilege, schema validation, correlation, idempotency, bounded retries, asynchronous error handling, monitoring and named ownership. Test and production credentials, controlled mapping changes and reconciliation totals reduce the chance that a technically successful sync hides an incomplete business outcome.
Reconcile Physical, Payment, and Accounting Evidence Before Closure
BOC combines event-driven processing with scheduled reconciliation. It can identify approved Brex requests without BCM orders, BCM orders without fulfillment, fulfilled orders without bills, bills without supported commercial references, payments without accepted ERP responses, credits still pending and delivered cards with unresolved identity or quantity exceptions.
Financial closure requires supported bill, payment or credit and ERP evidence. Operational closure requires the intended cards to be produced, delivered and accepted or a named authority to accept the variance. Neither side substitutes for the other, and a paid bill alone never proves correct fulfillment.
The final case records source demand, CCA version, Brex request and approval, budget or spend reference, PO or purchasing-card path, BCM order and delivery, bill and payment, ERP response, exceptions and closure authority. Procurement, finance, identity, operations and audit can understand the complete outcome from one trace.
Implement One Brex Business Card Journey First
Begin with one entity, one ERP, one worker population, one demand reason, one CCA policy, one BCM vendor record, one product, one Brex request type and one payment path. Confirm identity approval, spend authorization, ordering, delivery, billing, payment, ERP posting, reconciliation and ownership before expanding.
Test difficult paths deliberately: duplicate HCM events, stale identity, rejected requests, inactive vendors, duplicate BCM submissions, partial delivery, incorrect cards, invoice before receipt, duplicate invoice, PO overage, changed payment details, API errors, Brex rejection, ERP sync failure, returned payment, credit memo and uncertain acknowledgement.
Measure business outcomes rather than interface availability. Useful measures include qualified-demand accuracy, duplicate prevention, first-proof accuracy, request-to-order time, delivery-to-bill lag, supported-match rate, exception age, ERP-posting success, credit closure time and the percentage of cases with complete identity, physical and financial evidence.
Buyer Intent Bridge: What a Brex Integration Engagement Produces
Organizations do not need another isolated financial connector. They need an operating contract across workforce or campaign demand, public identity, purchasing, BCM execution, Bill Pay, payment and accounting. A BOC engagement can define the authority matrix, event model, data contracts, Brex integration method, security boundary, exception taxonomy, reconciliation controls and support model.
The architecture protects existing investments. HCM and CRM retain source authority, CCA governs printable identity, BCM remains the business-card ordering system and vendor, Brex governs configured spend and AP activity, and the ERP retains financial authority. BOC governs the transitions, evidence and accountable closure across those domains.
The first implementation should produce a reusable blueprint containing source-event rules, CCA approval contract, Brex request and spend design, BCM ordering contract, PO or purchasing-card mapping, Bill Pay and ERP interfaces, access controls, monitoring, reconciliation, ownership and measurable acceptance criteria.
Questions Integration Buyers Should Ask
- Which HCM or CRM event qualifies demand before CCA approval and a Brex request?
- Which role approves printable identity, purchasing spend, a physical variance, a bill exception and final closure?
- Which Brex request, spend limit, purchasing card, PO, Bill Pay and ERP capabilities are licensed and configured?
- Which references correlate the BOC case, CCA version, Brex request, BCM order, bill, payment and ERP record?
- How are duplicate orders, bills, payments and uncertain acknowledgements reconciled?
- What physical and financial evidence is required before closure?
Frequently Asked Questions
Does BOC replace Brex? No. Brex remains the configured spend and AP platform. BOC governs cross-system transitions, evidence and closure.
Is a Brex corporate card the same as a printed employee business card? No. The Brex card is a payment instrument. The printed card is a public identity artifact governed by CCA and fulfilled by BCM.
Does Brex approve printable business card identity? No. CCA governs printable identity. Brex governs configured financial activity.
Does a paid bill prove correct fulfillment? No. BCM delivery and acceptance evidence is still required.
Is a universal native connector claimed? No. The architecture uses customer-approved interfaces and validated licensed capabilities.
Connect one Brex purchasing and payment path to a governed business-card outcome. Business Ops Center can define the authority model, CCA identity approval, Brex request and spend controls, BCM ordering and fulfillment contract, Bill Pay and ERP integration, exception handling and reconciliation required for a controlled implementation. Start with one high-friction journey and turn it into a reusable enterprise integration pattern.